Live AMA With Financial Planner Cindy Marques
For our January 2021 Stepping Stones to Success Challenge, we collaborated with our partners, Paper & Coin and Space in the City, to help you start the new year on solid ground. As part of our efforts, we went live on Instagram to answer some of your burning questions.
First up, Paper & Coin. They are a remote team of financial experts who help Millennials gain control over their finances as well as gain confidence in managing them. The experts at Paper & Coin offer personalized coaching, educational courses, and accessible resources. For the challenge, they provided a free webinar on budgeting alongside a budget template to help participants start taking action on their finances.
To bring their knowledge to the table, Epilogue co-founder Daniel Goldgut sat down with Certified Financial Planner Cindy Marques for a live conversation about financial literacy. In case you missed it, here are the main takeaways from the discussion.
There’s nothing to feel guilty, shameful, or embarrassed about when it comes to talking about your finances.
We’ve all experienced that awkward conversation with a new person where we forget their name but are too embarrassed to ask. Take that feeling and multiply it by 100, and that’s how the majority of people feel about asking questions surrounding estate planning or financial planning.
People tend to think they are the only ones their age who haven’t made a Will yet. Or that they’re too educated to admit out loud they’ve never made a budget. But in Cindy and Daniel’s experience, the majority of their clients are in the same boat.
People haven’t taken the first step to addressing their finances because they’re too ashamed to start the conversation and ask the hard questions. Everyone thinks they’re the only one, but they’re not! And there’s no shame in asking for help.
The first step to financial success is to address your “debt demons” and “money wounds” head-on.
By facing the numbers and being honest about your finances, the looming fear of what’s going on with your money will quickly fade. For a lot of people, there’s an immediate cathartic relief when working with a financial planner.
It might be the first time they’ve unloaded their financial worries, said their goals out loud, and openly addressed their money situation. After that, the fear is gone!
Once you can account for every dollar coming in and every dollar coming out, you can honestly and intelligently make a plan about your finances.
Create an emergency fund of 3-6 months’ worth of your household expenses before you start investing.
Financial planners are often faced with the question of repaying debt versus investing. Cindy’s advice is to find a balance between doing both based on your situation.
For starters, if you’re carrying debt, you need an emergency fund that is not invested (that’s your 3-6 months of household expenses). Then take a look at the type of debt you have to repay. If it’s high-interest debt like credit cards, you don’t need to start investing. You need to focus on repayment. Student loans, on the other hand, typically have low-interest rates. If you’re able to expedite paying them off, focus on that before investing.
All in all, investing is very subjective to each individual’s situation and people often get hung up on what they’re “supposed” to do based on their age, income, peers, etc. The fact of the matter is that you need to weigh your individual options and make an informed decision from there.
Have open conversations about money at home. They go a long way for financial literacy and success.
Cindy’s path to becoming a financial planner stemmed from a common lack of financial literacy amongst herself and her peers. She found that most Millennials did not learn about finances in school nor did they have productive conversations about finances at home with their family.
Her advice to parents of the next generation is to be transparent about money in front of their kids. For example, when you’re grocery shopping you can plainly tell your kids why you bought one product instead of another based on the price, the quality, etc. Or you can give them a budget for their birthday present and take them shopping to choose their gift based on that budget so they can begin to understand the value of money.
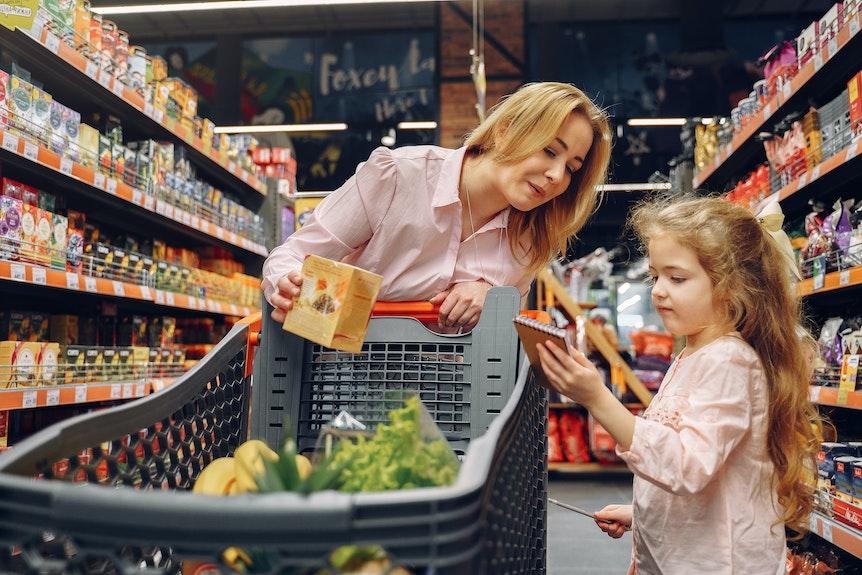
There are more concrete ways to directly provide financial literacy to children, but there’s a lot of value in parents openly discussing how they manage their money at home so their children aren’t afraid to talk about money when the time comes.
So, where do I start?
As with most big to-do items, getting started is often the hardest part. Ask yourself if it’s important to you to understand the inner workings of investing or if you’d like a more hands-off approach.
There are automated platforms that provide you with a portfolio based on how you answer a questionnaire. This can be a great place to start for many people!
But if you’re investing for the first time, it can be a very emotional and complicated game to play. It’s hard to keep your cool when things get rocky. That’s where a financial planner or investment advisor, like Paper & Coin, will come into play. They’ll guide you, provide advice, and keep you in check with your goals to help you make adjustments to your investments without making rash decisions.